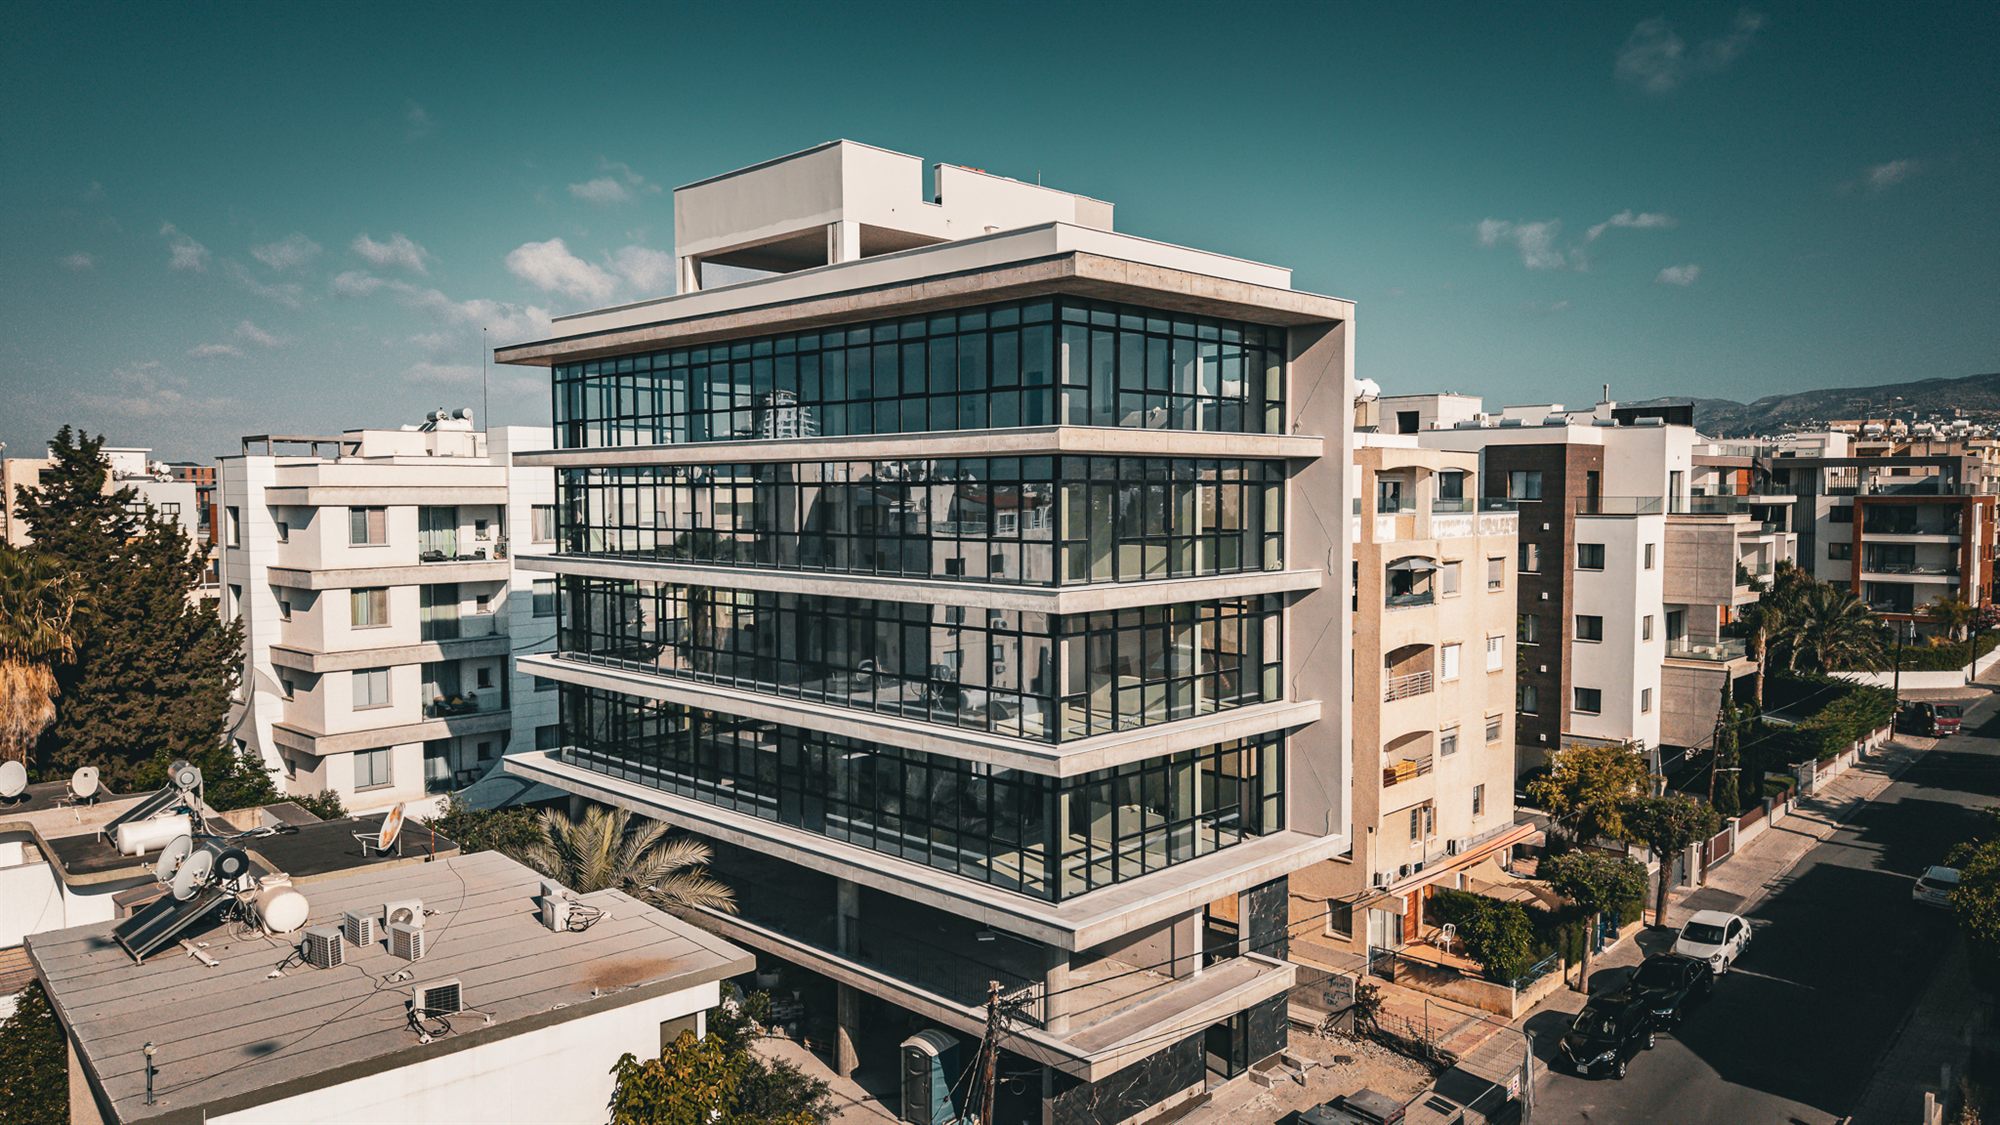
Decide whether a whole building is the right acquisition
Buying an entire office building is materially different from buying one office floor. It can suit an owner-occupier seeking a visible headquarters, a group that wants to combine its own space with future leasing, or an investor prepared to manage commercial lettings. It may be a poor fit for a buyer who only needs a small fixed workspace, cannot accommodate timing changes, or expects a passive return without a documented letting strategy.
Before examining finishes or views, write a one-page buyer brief. Set the required occupation date, the teams or tenants expected to use the building, minimum usable area, parking needs, likely fit-out budget, decision-makers and maximum all-in acquisition budget. This brief becomes the benchmark for the plans, areas and transaction documents.
Read the area schedule before relying on the headline size
Germasogeia Corporate Prime is presented as a planned standalone Class-A commercial office development in Potamos Germasogeias, Limassol, approximately 400 metres from the coast. Its stated gross total area is 1,934 m². Treat that as a figure to verify in the current schedule, drawings and proposed contract—not as a substitute for them.
Request a floor-by-floor schedule that separates office space, reception or common areas, covered and uncovered external areas, parking, storage and roof-garden components. Gross area is not automatically the space a business can fit out or lease. Ask the project team to explain the measurement basis in writing, then have an independent adviser review it if the number drives a lease model or purchase decision.
- The current area schedule and the drawings it refers to.
- A breakdown of the stated gross total against office, common and external areas.
- The latest specification and a list of what is included at handover.
- A clear comparison between the marketing summary and contract annexes.
Verify the elements that affect daily operation
The stated 18 parking spaces, four EV charging points and roof garden are commercially meaningful only when their position, allocation and operational responsibility are clear. Ask to see each on the latest drawings. Confirm whether charging points are delivered as installed working facilities or whether further equipment, connection or operating arrangements are required.
Obtain the current roof-garden layout, the scope included at handover, access arrangements and ongoing maintenance responsibilities. A roof area can be a useful executive or staff amenity, but only if it works with the intended occupation model and the buyer understands the obligations attached to it.
Treat the June 2026 date as a target, not a guarantee
The stated handover target is June 2026. A target date should prompt specific contract questions: what condition constitutes handover; which elements are included; how changes are documented; what notice the buyer receives; and what happens if the programme moves. Request the current construction update and a dated schedule, then compare both with the contract wording before committing funds.
For an owner-occupier, allow a separate interval for interior planning, furniture, IT and occupancy preparation. For an investor, avoid scheduling a tenant start date based only on a marketing delivery target. Property evidence comes first, contract review second, and occupation or leasing decisions only when their assumptions are supported.
Stress-test the rental scenario without turning it into a promise
The seller’s stated rental scenario is €49,000 per month, or €588,000 per year, described as approximately 6.8% gross before vacancy, tax, operating costs, fit-out and financing. It is a question to investigate, not a return to rely on.
Ask for the method behind the scenario. Is it calculated from a defined leasable area, and what rent, incentives, vacancy assumption and occupier profile does it use? Model at least three cases: the stated scenario, a slower lease-up with lower rent, and self-use with no external rental income. A gross percentage is not cash flow; independent advisers should test the numbers against the intended ownership, financing and leasing approach.
Keep ownership and VAT discussions factual
Some acquisitions may be discussed as a direct property purchase or through a company-share structure. Neither route should be marketed or assumed to produce a particular VAT, tax, financing or residency outcome. A share purchase can have different VAT implications; it is not automatic VAT avoidance. The buyer should obtain independent legal, tax and corporate advice on the exact entity, documents and transaction before a reservation or transfer.
Likewise, the stated 0% buyer commission and direct developer enquiry route should be confirmed in writing for this specific transaction. A clear schedule of parties, fees, responsibilities and conditions is more valuable than a broad marketing label.
- Provide the latest drawings and area schedule supporting the stated 1,934 m² gross total area.
- Show the 18 parking spaces and four EV charging points on the current plan and confirm allocation.
- Explain what is included in the roof garden at handover and who maintains it.
- Provide the current construction update and target handover programme.
- Explain the assumptions behind the €49,000 monthly rental scenario.
- Confirm the stated 0% buyer commission in the transaction documents.
Use the first enquiry to get the right evidence
Request current plans, availability and transaction documents through Another Cyprus, then have independent technical, legal and tax advisers test them against your operating brief before negotiating final terms. The guide price is stated at €8.7m plus VAT, but prices, availability, programme and transaction terms require current written verification.
This guide is general information, not legal, tax or investment advice. It is designed to make the first enquiry more precise and the next professional review more useful.
This guide is general information, not legal, tax, immigration, valuation or investment advice. Property details and market conditions change. Buyers should verify all material facts with independent qualified advisers.